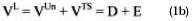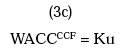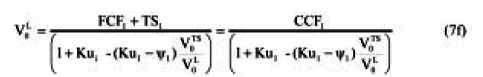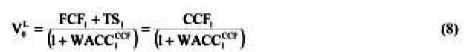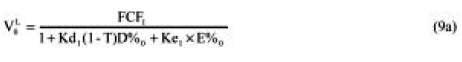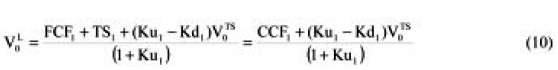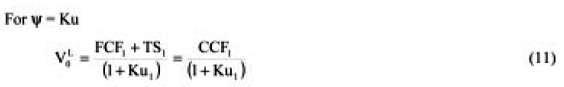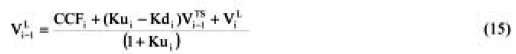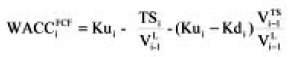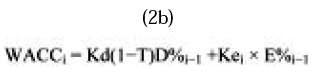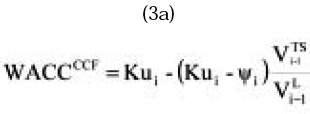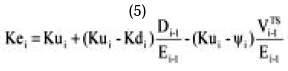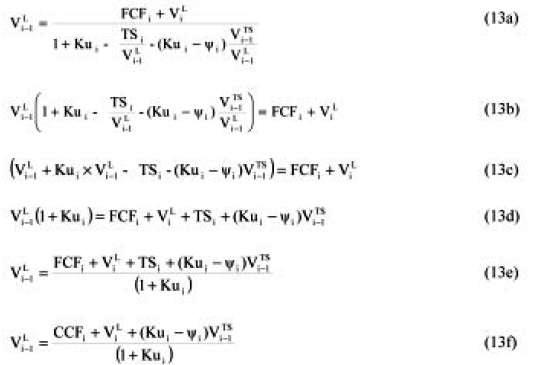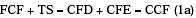
<?xml version="1.0" encoding="ISO-8859-1"?><article xmlns:mml="http://www.w3.org/1998/Math/MathML" xmlns:xlink="http://www.w3.org/1999/xlink" xmlns:xsi="http://www.w3.org/2001/XMLSchema-instance">
<front>
<journal-meta>
<journal-id>0123-5923</journal-id>
<journal-title><![CDATA[Estudios Gerenciales]]></journal-title>
<abbrev-journal-title><![CDATA[estud.gerenc.]]></abbrev-journal-title>
<issn>0123-5923</issn>
<publisher>
<publisher-name><![CDATA[Universidad Icesi]]></publisher-name>
</publisher>
</journal-meta>
<article-meta>
<article-id>S0123-59232006000100001</article-id>
<title-group>
<article-title xml:lang="en"><![CDATA[THERE EXISTS CIRCULARITY BETWEEN WACC AND VALUE? ANOTHER SOLUTION]]></article-title>
</title-group>
<contrib-group>
<contrib contrib-type="author">
<name>
<surname><![CDATA[Vélez-Pareja]]></surname>
<given-names><![CDATA[Ignacio]]></given-names>
</name>
<xref ref-type="aff" rid="A01"/>
</contrib>
<contrib contrib-type="author">
<name>
<surname><![CDATA[Benavides-Franco]]></surname>
<given-names><![CDATA[Julián]]></given-names>
</name>
<xref ref-type="aff" rid="A02"/>
</contrib>
</contrib-group>
<aff id="A01">
<institution><![CDATA[,Politécnico Grancolombiano  ]]></institution>
<addr-line><![CDATA[Bogotá ]]></addr-line>
<country>Colombia</country>
</aff>
<aff id="A02">
<institution><![CDATA[,ICESI  ]]></institution>
<addr-line><![CDATA[Cali ]]></addr-line>
<country>Colombia</country>
</aff>
<pub-date pub-type="pub">
<day>00</day>
<month>03</month>
<year>2006</year>
</pub-date>
<pub-date pub-type="epub">
<day>00</day>
<month>03</month>
<year>2006</year>
</pub-date>
<volume>22</volume>
<numero>98</numero>
<fpage>13</fpage>
<lpage>23</lpage>
<copyright-statement/>
<copyright-year/>
<self-uri xlink:href="http://www.scielo.org.co/scielo.php?script=sci_arttext&amp;pid=S0123-59232006000100001&amp;lng=en&amp;nrm=iso"></self-uri><self-uri xlink:href="http://www.scielo.org.co/scielo.php?script=sci_abstract&amp;pid=S0123-59232006000100001&amp;lng=en&amp;nrm=iso"></self-uri><self-uri xlink:href="http://www.scielo.org.co/scielo.php?script=sci_pdf&amp;pid=S0123-59232006000100001&amp;lng=en&amp;nrm=iso"></self-uri><abstract abstract-type="short" xml:lang="en"><p><![CDATA[Although we know there exists a simple approach to solve the circularity between value and the discount rate, known as the Adjusted Present Value proposed by Myers, 1974, it seems that practitioners still rely on the traditional Weighted Average Cost of Capital, WACC approach of weighting the cost of debt, Kd and the cost of equity, Ke and discounting the Free Cash Flow, FCF. We show how to solve circularity when calculating value with the free cash flow, FCF and the WACC. As a result of the solution we arrive at a known solution when we assume the discount rate of the taxsavings as Ke, the cost of unlevered equity: the capital cash flow, CCF discounted at Ku. When assuming Kd as the discount rate for the tax savings, we find an expression for calculating value that does not implies circularity. We do this for a single period and for N periods.]]></p></abstract>
<kwd-group>
<kwd lng="en"><![CDATA[Firm valuation]]></kwd>
<kwd lng="en"><![CDATA[cost of capital]]></kwd>
<kwd lng="en"><![CDATA[cash flows]]></kwd>
<kwd lng="en"><![CDATA[free cash flow]]></kwd>
<kwd lng="en"><![CDATA[capital cash flow]]></kwd>
<kwd lng="en"><![CDATA[WACC]]></kwd>
<kwd lng="en"><![CDATA[circularity]]></kwd>
</kwd-group>
</article-meta>
</front><body><![CDATA[   <font size="2" face="verdana">        <p align="right"><font size="4"><b>THERE EXISTS CIRCULARITY BETWEEN  WACC AND VALUE? ANOTHER  SOLUTION.</b></font></p>      <p align="right">Ignacio V&eacute;lez&shy;Pareja<sup>1</sup>, Juli&aacute;n Benavides&shy;Franco<sup>2</sup></p>      <p align="right"><sup>1</sup>Polit&eacute;cnico Grancolombiano  Bogot&aacute;, Colombia  <a href="mailto:ivelez@poligran.edu.co">ivelez@poligran.edu.co</a></p>      <p align="right"><sup>2</sup>ICESI  Cali, Colombia  <a href="mailto:jbenavid@icesi.edu.co">jbenavid@icesi.edu.co</a></p>      <p align="right">Fecha de recepción: 21&shy;10&shy;2005 Fecha de aceptación: 12&shy;11&shy;2005</p>  <hr />      <p><b>ABSTRACT</b></p>      <p>Although we know there exists a simple  approach to solve the circularity  between value and the discount rate,  known as the Adjusted Present Value  proposed by Myers, 1974, it seems  that practitioners still rely on the  traditional Weighted Average Cost of  Capital, WACC approach of weighting  the cost of debt, Kd and the cost  of equity, Ke and discounting the Free  Cash Flow, FCF. We show how to solve  circularity when calculating value  with the free cash flow, FCF and the  WACC. As a result of the solution we  arrive at a known solution when we  assume the discount rate of the taxsavings as Ke, the cost of unlevered  equity: the capital cash flow, CCF discounted  at Ku. When assuming Kd  as the discount rate for the tax savings,  we find an expression for calculating  value that does not implies  circularity. We do this for a single  period and for N periods.</p>      <p><b>KEY WORDS</b></p>      <p>Firm valuation, cost of capital, cash  flows, free cash flow, capital cash flow,  WACC, circularity</p>      ]]></body>
<body><![CDATA[<p>JEL CLASSIFICATION  M21, M40, M46, M41, G12, G31, J33</p>  <hr />      <p><font size="3"><b>INTRODUCTION</b></font></p>      <p>Although we know there exists a simple  approach to solve the circularity  between value and the discount rate,  known as the Adjusted Present Value  proposed by Myers, 1974, it seems  that practitioners still rely on the  traditional Weighted Average Cost of  Capital, WACC approach of weighting  the cost of debt, Kd and the cost  of equity, Ke and discounting the Free  Cash Flow, FCF. We show how to solve  circularity when calculating value  with the free cash flow, FCF and the  WACC. As a result of the solution we  arrive at a known solution when we  assume the discount rate of the tax  savings as Ke, the cost of unlevered  equity: the capital cash flow, CCF discounted  at Ku. When assuming Kd  as the discount rate for the tax savings,  we find an expression for calculating  value that does not implies  circularity. We do this for a single  period and for N periods.</p>      <p>The typical solution for solving the  circularity between value and WACC  is to activate the option for iteration  in a modern spreadsheet (V&eacute;lez&shy;Pareja  and Tham, 2000</p>      <p>Tham and V&eacute;lez&shy;Pareja, 2004, and  V&eacute;lez&shy;Pareja and Tham, 2005).  However, this approach seems to be  not easy to apply. We have examined  the analytical solution of this problem  and found what is known well before:  when discounting with the proper  discount rate the CCF will give identical  answer to the calculation of value  with the FCF discounted at the  weighted average cost of capital,  WACC.</p>     <p><font size="3"><b>THE PRACTICAL SOLUTION OF      CIRCULARITY</b></font></p>          <p>The solution of circularity is very simple.      This problem can be easily solved:      in the Excel spreadsheet select      Tools, then select Options, and there,      select the tab Calculate and tick      the option Iterations. Done this, the      formulas for WACC and Ke, (the cost      of the levered equity), that imply circularity,      can be constructed. (See,      V&eacute;lez&shy;Pareja and Tham, 2000 and      2005, Tham and V&eacute;lez&shy;Pareja, 2004).      The analytical solution is simple as      well.</p>          <p><font size="3"><b>AN ANALYTICAL SOLUTION      FOR CIRCULARITY</b></font></p>         <p>Modigliani and Miller (1958 and      1963), in illuminating and seminal      works defined the relationship between      cash flows and values. These      are the free cash flow, FCF, the cash      flow<a href="#1"><sup>1</sup></a> to debt, CFD, the cash flow to      equity, CFE, the tax savings, TS and      the capital cash flow1 and their corresponding      values. These relationships      are:</p>     <p><img src="/img/revistas/eg/v22n98/n98a01e1.jpg" /></p>     ]]></body>
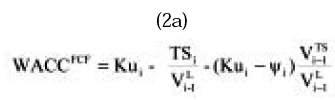
<body><![CDATA[<p><img src="/img/revistas/eg/v22n98/n98a01e2.jpg" /></p>     <p>Where V<sup>L</sup> is the levered value of the firm, V<sup>Un</sup> is the unlevered value of the firm, VTS is the value of TS, D is the market value of debt and E is the market value of equity.</p>     <p>In Taggart, 1991, Tham and Velez&shy; Pareja, 2002 and 2004, V&eacute;lez&shy;Pareja and Burbano&shy;P&eacute;rez, 2003 and 2005 it is shown the general formulation for the WACC and the Ke, as follows</p> <ol>    <li>The general expression for the WACC for the free cash flow, FCF, is     <p><a name="#ecua1"></a><img src="/img/revistas/eg/v22n98/n98a01e3.jpg" /></p>     <p>A particular and special case of <a href="#ecua1">(2a)</a> is the traditional expression for WACC:</p></li>     <p><a name="#ecua3"></a><img src="/img/revistas/eg/v22n98/n98a01e4.jpg" /></p>     <p>Where &Psi; is the discount rate for the TS and Ku is the unlevered cost of equity.</p></li>     <li>For discounting the Capital Cash Flow CCF, (CFD + CFE = FCF + TS), we use the general formulation for WACC<sup>CCF</sup>     <p><a name="#ecua2"></a><img src="/img/revistas/eg/v22n98/n98a01e5.jpg" /></p>     ]]></body>
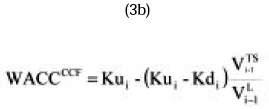
<body><![CDATA[<p>Depending on the assumption for the discount rate for the tax savings &Psi;, we have the WACC for the CCF as follows:</p>     <p>For &Psi; = Kd, the cost of debt</p>     <p><img src="/img/revistas/eg/v22n98/n98a01e6.jpg" /></p>     <p>For &Psi; = Ku </p>     <p><img src="/img/revistas/eg/v22n98/n98a01e7.jpg" /></p></li>     <li>    <p>If we use CFE we should discount it with (in this case we have to add the value o debt to obtain the total value)</p>     <p><b>Single periodo</b></p>     <p><a name="#ecua6"></a><img src="/img/revistas/eg/v22n98/n98a01e8.jpg" /></p>     <p>We have for a single period:</p>     ]]></body>
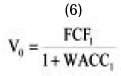
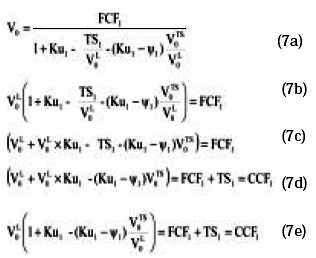
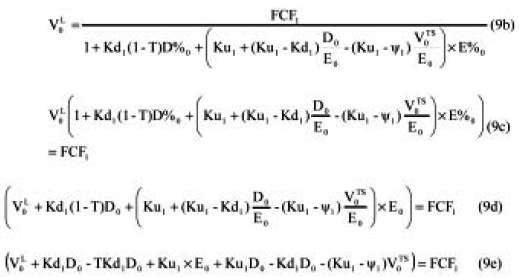
<body><![CDATA[<p><a name="#ecua4"></a><img src="/img/revistas/eg/v22n98/n98a01e9.jpg" /></p></li>    </ol>     <p><font size="3"><b>USING A GENERAL EXPRESSION FOR WACC</b></font></p>     <p>If we replace equation <a href="#ecua1">2a</a> into equation <a href="#ecua4">(6)</a> we find:</p>     <p><img src="/img/revistas/eg/v22n98/n98a01e10.jpg" /></p>     <p><img src="/img/revistas/eg/v22n98/n98a01e11.jpg" /></p>     <p>This expression is just (see <a href="#ecua2"> equation (3a)</a>)</p>     <p><img src="/img/revistas/eg/v22n98/n98a01e12.jpg" /></p>      <p><font size="3"><b>USING THE TRADITIONAL AND SPECIAL EXPRESSION FOR WACC</b></font></p>     <p>If we replace <a href="#ecua3">(2b)</a> in <a href="#ecua4">(6)</a> and replace Ke for its general expression <a href="#ecua6">(5)</a> we have</p>     ]]></body>
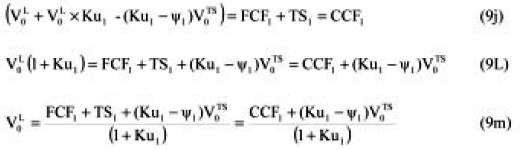
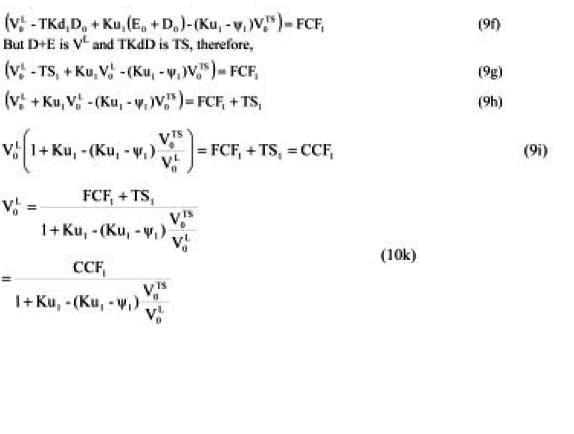
<body><![CDATA[<p><a name="ecua5"></a><img src="/img/revistas/eg/v22n98/n98a01e13.jpg" /></p>     <p>Replacing Ke in <a href="#ecua5">(9a)</a> with <a href="#ecua6">(5)</a> we have</p>     <p><img src="/img/revistas/eg/v22n98/n98a01e14.jpg" /></p>     <p>Simplifying,</p>     <p><a name="#ecua7"></a><img src="/img/revistas/eg/v22n98/n98a01e15.jpg" /></p>     <p>Again, this expression is the value of the CCF and the discount rate is <a href="#ecua2">(3)</a>. In both cases we find circularity again. In order to solve it we depart from <a href="#ecua7">(9h)</a></p>     <p><img src="/img/revistas/eg/v22n98/n98a01e16.jpg" /></p>     <p>And with the circularity fully solved we have for each case, for &psi; = Kd</p>     <p><img src="/img/revistas/eg/v22n98/n98a01e17.jpg" /></p>     <p>This means that when solving the circularity and assuming &psi; = Kd we need to &quot;adjust&quot; the CCF by (Ku<sub>1</sub>&shy;Kd<sub>1</sub>) V<sub>0</sub><sup> TS</sup>.</p>     ]]></body>
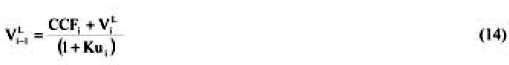
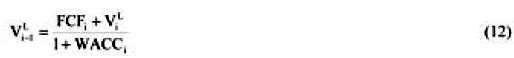
<body><![CDATA[<p><img src="/img/revistas/eg/v22n98/n98a01e18.jpg" /></p>     <p>Observe the clean, neat and easy formulation when we assume &psi; = Ku</p>     <p><font size="3"><b>THE N&shy;PERIOD CASE</b></font></p>     <p>There is a recursive equation to calculate the present value of a cash flow for any discount rate:</p>     <p><a name="#ecua8"></a><img src="/img/revistas/eg/v22n98/n98a01e19.jpg" /></p>     <p>Replacing <a href="#ecua3">(2a)</a> into <a href="#ecua8">(12)</a> we have,</p>    <p> </p>    <p><a name="#ecua9"></a><img src="/img/revistas/eg/v22n98/n98a01e20.jpg" /></p>     <p>When &psi; =Ku</p>     <p><img src="/img/revistas/eg/v22n98/n98a01e21.jpg" /></p>     ]]></body>
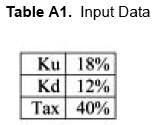
<body><![CDATA[<p>And this is the recursive equation to calculate the present value of a cash flow (in this case with the CCF and Ku as discount rate).</p>     <p>When &psi; =Kd</p>     <p><img src="/img/revistas/eg/v22n98/n98a01e22.jpg" /></p>     <p>This is the same equation as before using the recursive equation to calculate the present value of a cash flow, in this case, the &quot;Adjusted&quot; CCF.</p>     <p><font size="3"><b>CONCLUDING REMARKS</b></font></p>     <p>We have shown that circularity can be solved analytically. The interesting finding is that when solving for circularity we arrive at a well know result: the discounting of the capital cash flow, CCF.</p>     <p>When we assume that the discount rate for the tax savings is Ku, the cost of unlevered equity, the solution is very simple: discount it with Ku. If we assume that the discount rate is Kd, then we have either to adjust the CCF with an amount function of the value of the tax savings, or we use the traditional expression for the CCF and discount it with Ku adjusted with some percent that is function of the value of the tax savings.</p>     <p><font size="3"><b>APPENDIX</b></font></p>     <p><b>AN EXAMPLE</b></p>      <p>Assume the following input data:</p>     ]]></body>
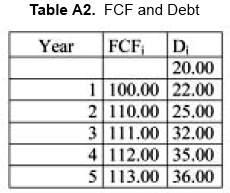
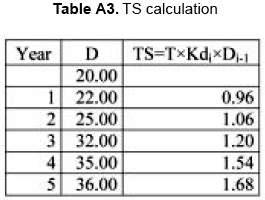
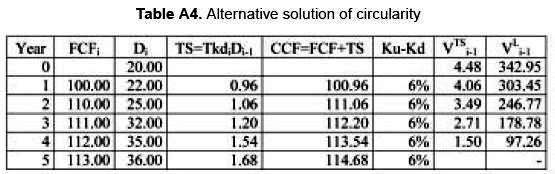
<body><![CDATA[<p>    <center><img src="/img/revistas/eg/v22n98/n98a01t1.jpg" /></center></p>     <p>And the following FCF and debt, D</p>     <p>    <center><img src="/img/revistas/eg/v22n98/n98a01t2.jpg" /></center></p>     <p>From this information we can calculate TS</p>     <p>    <center><img src="/img/revistas/eg/v22n98/n98a01t3.jpg" /></center></p>     <p><font size="3"><b>PROPOSED APPROACH</b></font></p>     <p>Using <a href="#ecua9">(13f)</a> and assuming &Psi; = Kd</p>     ]]></body>
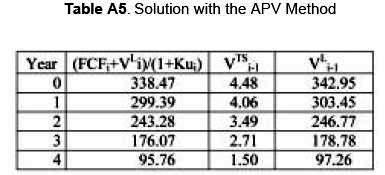
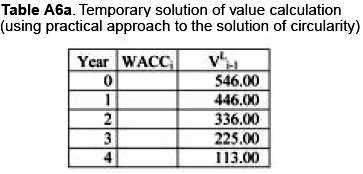
<body><![CDATA[<p><img src="../img/revistas/eg/v22n98//n98a01e23.jpg" /></p>     <p>We have</p>     <p>    <center><img src="/img/revistas/eg/v22n98/n98a01t4.jpg" /></center></p>     <p><font size="3"><b>THE APV METHOD</b></font></p>     <p>Using the Adjusted Present Value, APV we have</p>     <p>    <center><img src="/img/revistas/eg/v22n98/n98a01t5.jpg" /></center></p>     <p><font size="3"><b>PRACTICAL SOLUTION OF CIRCULARITY</b></font></p>     <p>Finally using the practical solution for perpetuity we have Temporal solution for WACC = 0%</p>     ]]></body>
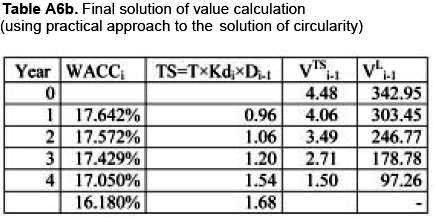
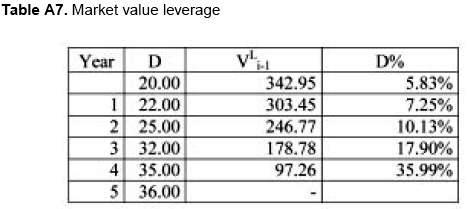
<body><![CDATA[<p>    <center><img src="/img/revistas/eg/v22n98/n98a01t6.jpg" /></center></p>     <p>Observe that this is not the final solution because we are using WACC = 0%. Now, introducing the general formulation <a href="#ecua1">(2a)</a> for WACC<sup>FCF</sup> and solving the circularity, we have</p>     <p><img src="/img/revistas/eg/v22n98/n98a01e24.jpg" /></p>     <p>    <center><img src="/img/revistas/eg/v22n98/n98a01t7.jpg" /></center></p>     <p>As can be seen, the circularity can be solved not only with the practical method, but using formulation <a href="#ecua9">(13f)</a>.</p>     <p>Observe as well that we do not need to set any target leverage. The approach allows for non constant leverage that is the usual situation in reality.</p>     <p>    <center><img src="/img/revistas/eg/v22n98/n98a01t8.jpg" /></center></p>     ]]></body>
<body><![CDATA[<p>Note: The paper can be accesed at the SSRN (Social Science Research Network) <a href="http://www.ssrn.com/" target="_blank">www.ssrn.com</a></p>            <p><b>FOOTNOTES</b></p>     <p><a name="#1">1.</a>The Capital Cash Flow, CCF, is the essence of the original Modigliani and Miller proposal in 1958; however, it was popularized by Ruback, 2000.</p> <hr />      <p><font size="3"><b>REFERENCES</b></font></p>      <!-- ref --><p>1. Modigliani, F. &amp;    Miller M. H.(1958).    The Cost of Capital, Corporation Taxes and the Theory of Investment, <i>The American Economic Review</i>. XLVIII, 261&shy;297.&nbsp;&nbsp;&nbsp;&nbsp;&nbsp;&nbsp;&nbsp;&nbsp;[&#160;<a href="javascript:void(0);" onclick="javascript: window.open('/scielo.php?script=sci_nlinks&ref=000117&pid=S0123-5923200600010000100001&lng=','','width=640,height=500,resizable=yes,scrollbars=1,menubar=yes,');">Links</a>&#160;]<!-- end-ref --><!-- ref --><p>2.    Modigliani, F. &amp;    Miller, M. (1959).    The Cost of Capital, Corporation Finance, and the Theory of Investment: Reply. <i>The American Economic Review</i>. XLIX,524&shy;527.&nbsp;&nbsp;&nbsp;&nbsp;&nbsp;&nbsp;&nbsp;&nbsp;[&#160;<a href="javascript:void(0);" onclick="javascript: window.open('/scielo.php?script=sci_nlinks&ref=000118&pid=S0123-5923200600010000100002&lng=','','width=640,height=500,resizable=yes,scrollbars=1,menubar=yes,');">Links</a>&#160;]<!-- end-ref --><!-- ref --><p>3. Modigliani, F. &amp; Miller, M. H.  (1963). Corporate Income Taxes and the Cost of Capital: A Correction. <i>The American Economic Review</i>. LIII, 433&shy;443.&nbsp;&nbsp;&nbsp;&nbsp;&nbsp;&nbsp;&nbsp;&nbsp;[&#160;<a href="javascript:void(0);" onclick="javascript: window.open('/scielo.php?script=sci_nlinks&ref=000119&pid=S0123-5923200600010000100003&lng=','','width=640,height=500,resizable=yes,scrollbars=1,menubar=yes,');">Links</a>&#160;]<!-- end-ref --><!-- ref --><p>4. Myers, S. C.  (1974). Interactions of Corporate Financing and Investment Decisions: Implications for Capital Budgeting. <i>Journal of Finance</i>. 29, 1&shy;25.&nbsp;&nbsp;&nbsp;&nbsp;&nbsp;&nbsp;&nbsp;&nbsp;[&#160;<a href="javascript:void(0);" onclick="javascript: window.open('/scielo.php?script=sci_nlinks&ref=000120&pid=S0123-5923200600010000100004&lng=','','width=640,height=500,resizable=yes,scrollbars=1,menubar=yes,');">Links</a>&#160;]<!-- end-ref --><!-- ref --><p>5. Taggart, Jr. &amp; Robert A. (1991). Consistent Valuation Cost of Capital Expressions with Corporate and Personal Taxes. <i>Financial Management, Autumn,</i>8&shy;20.&nbsp;&nbsp;&nbsp;&nbsp;&nbsp;&nbsp;&nbsp;&nbsp;[&#160;<a href="javascript:void(0);" onclick="javascript: window.open('/scielo.php?script=sci_nlinks&ref=000121&pid=S0123-5923200600010000100005&lng=','','width=640,height=500,resizable=yes,scrollbars=1,menubar=yes,');">Links</a>&#160;]<!-- end-ref --><!-- ref --><p>6. Tham, J. &amp; V&eacute;lez&shy;Pareja, I.  (2002). An Embarrassment of Riches: Winning Ways to Value with the WACC. Working Paper en <i>SSRN, Social Science Research Network</i>, <a href="http://papers.ssrn.com/sol3/papers.cfm?abstract_id=466721" target="_blank">http://papers.ssrn.com/sol3/ papers.cfm?abstract_id=352180</a>.&nbsp;&nbsp;&nbsp;&nbsp;&nbsp;&nbsp;&nbsp;&nbsp;[&#160;<a href="javascript:void(0);" onclick="javascript: window.open('/scielo.php?script=sci_nlinks&ref=000122&pid=S0123-5923200600010000100006&lng=','','width=640,height=500,resizable=yes,scrollbars=1,menubar=yes,');">Links</a>&#160;]<!-- end-ref --><!-- ref --><p>7. Tham, J. &amp; V&eacute;lez&shy;Pareja, I.  (2004). <i>Principles of Cash Flow Valuation. An Integrated Market Approach.</i> S.L: Academic Press.&nbsp;&nbsp;&nbsp;&nbsp;&nbsp;&nbsp;&nbsp;&nbsp;[&#160;<a href="javascript:void(0);" onclick="javascript: window.open('/scielo.php?script=sci_nlinks&ref=000123&pid=S0123-5923200600010000100007&lng=','','width=640,height=500,resizable=yes,scrollbars=1,menubar=yes,');">Links</a>&#160;]<!-- end-ref --><!-- ref --><p>8. V&eacute;lez&shy;Pareja, I. &amp; Tham, J. (2000). A Note on the Weighted Average Cost of Capital WACC. <i>Social Science Research Network.</i>&nbsp;&nbsp;&nbsp;&nbsp;&nbsp;&nbsp;&nbsp;&nbsp;[&#160;<a href="javascript:void(0);" onclick="javascript: window.open('/scielo.php?script=sci_nlinks&ref=000124&pid=S0123-5923200600010000100008&lng=','','width=640,height=500,resizable=yes,scrollbars=1,menubar=yes,');">Links</a>&#160;]<!-- end-ref --><!-- ref --><p>9. V&eacute;lez&shy;Pareja, I. &amp; Burbano&shy; P&eacute;rez, A. (2003, November 9<sup>th</sup>). “A Practical Guide for Consistency in Valuation: Cash Flows, Terminal Value and Cost of Capital”  (9<sup>th</sup> november 2003). <a href="http://papers.ssrn.com/sol3/papers.cfm?abstract_id=466721" target="_blank">http://ssrn.com/abstract=466721</a>&nbsp;&nbsp;&nbsp;&nbsp;&nbsp;&nbsp;&nbsp;&nbsp;[&#160;<a href="javascript:void(0);" onclick="javascript: window.open('/scielo.php?script=sci_nlinks&ref=000125&pid=S0123-5923200600010000100009&lng=','','width=640,height=500,resizable=yes,scrollbars=1,menubar=yes,');">Links</a>&#160;]<!-- end-ref --><!-- ref --><p>10. V&eacute;lez&shy;Pareja, I. &amp; Burbano&shy;P&eacute;rez, A. (2005). Consistency in Valuation: A Practical Guide. SSRN <a href="http://papers.ssrn.com/sol3/papers.cfm?abstract_id=758664" target="_blank">http://papers.ssrn.com/sol3/papers.cfm?abstract_id=758664</a>&nbsp;&nbsp;&nbsp;&nbsp;&nbsp;&nbsp;&nbsp;&nbsp;[&#160;<a href="javascript:void(0);" onclick="javascript: window.open('/scielo.php?script=sci_nlinks&ref=000126&pid=S0123-5923200600010000100010&lng=','','width=640,height=500,resizable=yes,scrollbars=1,menubar=yes,');">Links</a>&#160;]<!-- end-ref --><!-- ref --><p>11. V&eacute;lez&shy;Pareja, I. &amp; Tham, J.  (2005). <i>Proper Solution of Circularity in the Interactions of Corporate Financing and Investment Decisions: A Reply to the Financing Present Value Approach.</i> Working Paper en SSRN: Social Science Research Network.Forthcoming in Management Research News 28 (7).2005 en <a href="http://papers.ssrn.com/sol3/papers.cfm?abstract_id=653222" target="_blank">http://papers.ssrn.com/sol3/papers.cfm?abstract_id=653222.</a>.&nbsp;&nbsp;&nbsp;&nbsp;&nbsp;&nbsp;&nbsp;&nbsp;[&#160;<a href="javascript:void(0);" onclick="javascript: window.open('/scielo.php?script=sci_nlinks&ref=000127&pid=S0123-5923200600010000100011&lng=','','width=640,height=500,resizable=yes,scrollbars=1,menubar=yes,');">Links</a>&#160;]<!-- end-ref --> ]]></body><back>
<ref-list>
<ref id="B1">
<label>1</label><nlm-citation citation-type="journal">
<person-group person-group-type="author">
<name>
<surname><![CDATA[Modigliani]]></surname>
<given-names><![CDATA[F.]]></given-names>
</name>
<name>
<surname><![CDATA[Miller]]></surname>
<given-names><![CDATA[M. H.]]></given-names>
</name>
</person-group>
<article-title xml:lang="en"><![CDATA[The Cost of Capital, Corporation Taxes and the Theory of Investment]]></article-title>
<source><![CDATA[The American Economic Review]]></source>
<year>1958</year>
<volume>XLVIII</volume>
<page-range>261-297</page-range></nlm-citation>
</ref>
<ref id="B2">
<label>2</label><nlm-citation citation-type="journal">
<person-group person-group-type="author">
<name>
<surname><![CDATA[Modigliani]]></surname>
<given-names><![CDATA[F.]]></given-names>
</name>
<name>
<surname><![CDATA[Miller]]></surname>
<given-names><![CDATA[M.]]></given-names>
</name>
</person-group>
<article-title xml:lang="en"><![CDATA[The Cost of Capital, Corporation Finance, and the Theory of Investment: Reply]]></article-title>
<source><![CDATA[The American Economic Review]]></source>
<year>1959</year>
<volume>XLIX</volume>
<page-range>524-527</page-range></nlm-citation>
</ref>
<ref id="B3">
<label>3</label><nlm-citation citation-type="journal">
<person-group person-group-type="author">
<name>
<surname><![CDATA[Modigliani]]></surname>
<given-names><![CDATA[F.]]></given-names>
</name>
<name>
<surname><![CDATA[Miller]]></surname>
<given-names><![CDATA[M. H.]]></given-names>
</name>
</person-group>
<article-title xml:lang="en"><![CDATA[Corporate Income Taxes and the Cost of Capital: A Correction]]></article-title>
<source><![CDATA[The American Economic Review]]></source>
<year>1963</year>
<volume>LIII</volume>
<page-range>433-443</page-range></nlm-citation>
</ref>
<ref id="B4">
<label>4</label><nlm-citation citation-type="journal">
<person-group person-group-type="author">
<name>
<surname><![CDATA[Myers]]></surname>
<given-names><![CDATA[S. C.]]></given-names>
</name>
</person-group>
<article-title xml:lang="en"><![CDATA[Interactions of Corporate Financing and Investment Decisions: Implications for Capital Budgeting]]></article-title>
<source><![CDATA[Journal of Finance]]></source>
<year>1974</year>
<volume>29</volume>
<page-range>1-25</page-range></nlm-citation>
</ref>
<ref id="B5">
<label>5</label><nlm-citation citation-type="journal">
<person-group person-group-type="author">
<name>
<surname><![CDATA[Taggart]]></surname>
<given-names><![CDATA[Jr.]]></given-names>
</name>
<name>
<surname><![CDATA[Robert]]></surname>
<given-names><![CDATA[A.]]></given-names>
</name>
</person-group>
<article-title xml:lang="en"><![CDATA[Consistent Valuation Cost of Capital Expressions with Corporate and Personal Taxes]]></article-title>
<source><![CDATA[Financial Management, Autumn]]></source>
<year>1991</year>
<page-range>8-20</page-range></nlm-citation>
</ref>
<ref id="B6">
<label>6</label><nlm-citation citation-type="book">
<person-group person-group-type="author">
<name>
<surname><![CDATA[Tham]]></surname>
<given-names><![CDATA[J.]]></given-names>
</name>
<name>
<surname><![CDATA[Vélez-Pareja]]></surname>
<given-names><![CDATA[I.]]></given-names>
</name>
</person-group>
<source><![CDATA[An Embarrassment of Riches: Winning Ways to Value with the WACC]]></source>
<year>2002</year>
<publisher-name><![CDATA[Working Paper en SSRN, Social Science Research Network]]></publisher-name>
</nlm-citation>
</ref>
<ref id="B7">
<label>7</label><nlm-citation citation-type="book">
<person-group person-group-type="author">
<name>
<surname><![CDATA[Tham]]></surname>
<given-names><![CDATA[J.]]></given-names>
</name>
<name>
<surname><![CDATA[Vélez-Pareja]]></surname>
<given-names><![CDATA[I.]]></given-names>
</name>
</person-group>
<source><![CDATA[Principles of Cash Flow Valuation: An Integrated Market Approach]]></source>
<year>2004</year>
<publisher-loc><![CDATA[S.L ]]></publisher-loc>
<publisher-name><![CDATA[Academic Press]]></publisher-name>
</nlm-citation>
</ref>
<ref id="B8">
<label>8</label><nlm-citation citation-type="book">
<person-group person-group-type="author">
<name>
<surname><![CDATA[Vélez-Pareja]]></surname>
<given-names><![CDATA[I.]]></given-names>
</name>
<name>
<surname><![CDATA[Tham]]></surname>
<given-names><![CDATA[J.]]></given-names>
</name>
</person-group>
<source><![CDATA[A Note on the Weighted Average Cost of Capital WACC]]></source>
<year>2000</year>
<publisher-name><![CDATA[Social Science Research Network]]></publisher-name>
</nlm-citation>
</ref>
<ref id="B9">
<label>9</label><nlm-citation citation-type="">
<person-group person-group-type="author">
<name>
<surname><![CDATA[Vélez-Pareja]]></surname>
<given-names><![CDATA[I.]]></given-names>
</name>
<name>
<surname><![CDATA[Burbano- Pérez]]></surname>
<given-names><![CDATA[A.]]></given-names>
</name>
</person-group>
<source><![CDATA[A Practical Guide for Consistency in Valuation: Cash Flows, Terminal Value and Cost of Capital]]></source>
<year>2003</year>
<month>, </month>
<day>No</day>
</nlm-citation>
</ref>
<ref id="B10">
<label>10</label><nlm-citation citation-type="book">
<person-group person-group-type="author">
<name>
<surname><![CDATA[Vélez-Pareja]]></surname>
<given-names><![CDATA[I.]]></given-names>
</name>
<name>
<surname><![CDATA[Burbano-Pérez]]></surname>
<given-names><![CDATA[A.]]></given-names>
</name>
</person-group>
<source><![CDATA[Consistency in Valuation: A Practical Guide]]></source>
<year>2005</year>
<publisher-name><![CDATA[SSRN]]></publisher-name>
</nlm-citation>
</ref>
<ref id="B11">
<label>11</label><nlm-citation citation-type="book">
<person-group person-group-type="author">
<name>
<surname><![CDATA[Vélez-Pareja]]></surname>
<given-names><![CDATA[I.]]></given-names>
</name>
<name>
<surname><![CDATA[Tham]]></surname>
<given-names><![CDATA[J.]]></given-names>
</name>
</person-group>
<source><![CDATA[Proper Solution of Circularity in the Interactions of Corporate Financing and Investment Decisions: A Reply to the Financing Present Value Approach]]></source>
<year>2005</year>
<publisher-name><![CDATA[Working Paper en SSRN: Social Science Research Network]]></publisher-name>
</nlm-citation>
</ref>
</ref-list>
</back>
</article>